Medicare in Pennsylvania provides health coverage for millions of older adults and certain younger people who qualify because of disability or specific medical conditions. But becoming eligible for Medicare does not mean everyone receives the same coverage.
Pennsylvania residents may have decisions to make about Original Medicare, Medicare Advantage, prescription drug coverage, and Medicare Supplement insurance. Understanding how these pieces work together can make it easier to choose coverage that fits your health needs, budget, prescriptions, and preferred doctors.
This guide explains the basics of Medicare in Pennsylvania and some of the choices you may encounter when becoming eligible.
What Is Medicare?
Medicare is a federal health insurance program primarily for people age 65 and older. Some people younger than 65 may also qualify because of a disability, End-Stage Renal Disease (ESRD), or ALS.
Medicare is different from Pennsylvania’s health insurance marketplace. If you’re looking for individual or family coverage before becoming eligible for Medicare, learn more in our guide to Pennie and Pennsylvania’s Health Insurance Marketplace.
Unlike an individual or family health insurance policy, Medicare coverage is individual. Spouses do not enroll together simply because one spouse becomes eligible.
Medicare is divided into different parts that cover different types of healthcare services. Medicare
What Are the Different Parts of Medicare?
One of the first things to understand about Medicare is the difference between Parts A, B, C, and D.
Medicare Part A — Hospital Insurance
Medicare Part A primarily helps cover inpatient hospital care.
It can also help cover eligible skilled nursing facility care, hospice care, and certain home health services.
Many people qualify for premium-free Part A based on their or their spouse’s work history and payment of Medicare taxes.
Medicare Part B — Medical Insurance
Medicare Part B helps cover many of the medical services people receive outside of an inpatient hospital stay.
These can include:
- Doctor and other healthcare provider services
- Outpatient care
- Certain home healthcare
- Durable medical equipment
- Preventive services and screenings
Together, Part A and Part B are commonly called Original Medicare. Medicare
Medicare Part C — Medicare Advantage
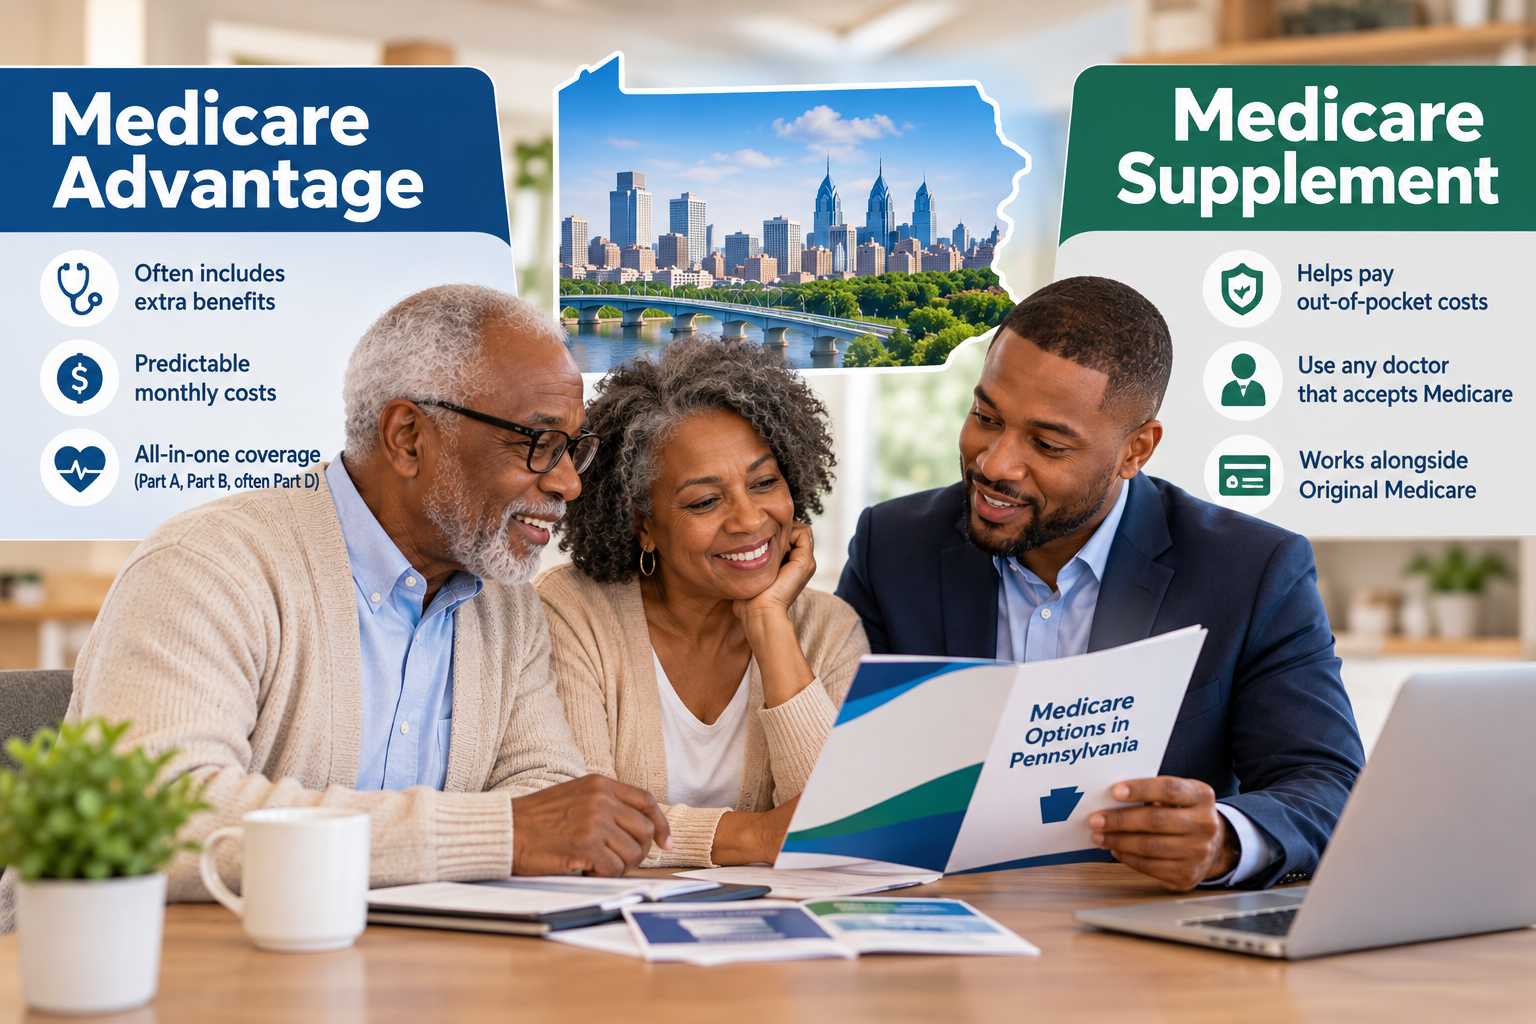
Medicare Advantage, also called Part C, is another way to receive Medicare coverage.
Instead of receiving healthcare coverage directly through Original Medicare, you enroll in a Medicare-approved plan offered by a private insurance company.
You generally need both Medicare Part A and Part B to join a Medicare Advantage plan.
Medicare Advantage plans provide Part A and Part B benefits and many plans also include prescription drug coverage. Depending on the plan and service area, plans may offer additional benefits not included under Original Medicare.
Plan availability, provider networks, benefits and costs can differ by location, which makes comparing Pennsylvania Medicare Advantage plans carefully important. Medicare
Medicare Part D — Prescription Drug Coverage
Medicare Part D helps cover prescription medications.
People using Original Medicare can purchase a separate Medicare drug plan from a private insurance company.
Many Medicare Advantage plans instead include Part D prescription drug coverage as part of the plan.
Because formularies, pharmacies and costs can vary between plans, your current medications should be considered when comparing coverage. Medicare
Original Medicare vs. Medicare Advantage in Pennsylvania
This is one of the biggest decisions many Pennsylvania Medicare beneficiaries face.
With Original Medicare, the federal government administers your Part A and Part B benefits. You can generally receive covered care from any doctor or hospital in the United States that accepts Medicare.
You can also choose a standalone Part D plan for prescription drugs and may consider Medicare Supplement insurance to help with certain out-of-pocket expenses.
With Medicare Advantage, you receive your Medicare benefits through a Medicare-approved private insurance plan.
Depending on the plan, you may need to use a provider network and follow plan rules for certain services.
Neither option is automatically best for everyone.
Your decision may depend on your doctors, prescriptions, travel habits, healthcare needs, budget and preference for how your coverage is structured. Medicare
What Is Medicare Supplement Insurance?
Medicare Supplement insurance is commonly called Medigap.
These policies are sold by private insurance companies and are designed to help pay certain out-of-pocket costs left by Original Medicare, such as some deductibles, coinsurance and copayments.
Medigap works with Original Medicare. It is not the same thing as Medicare Advantage.
In fact, you cannot use a Medigap policy to supplement a Medicare Advantage plan.
Medigap policies are standardized, although premiums can vary between insurance companies and other factors can affect availability and price. Medicare
When Can You Enroll in Medicare in Pennsylvania?
For many people, the first opportunity to enroll is their Initial Enrollment Period.
Generally, this seven-month period:
- Begins three months before the month you turn 65
- Includes the month you turn 65
- Ends three months after the month you turn 65
Some people are automatically enrolled in Medicare, while others need to actively enroll.
If you are still working at age 65 or covered through a spouse’s current employer, your situation may be different. Employer size, type of coverage and other factors can affect whether delaying Part B is appropriate.
Don’t assume that simply having some form of health coverage means you can delay Medicare without consequences. Verify how your existing coverage coordinates with Medicare before making that decision. Medicare
What Is the Medicare Open Enrollment Period?
Medicare’s annual Open Enrollment Period runs from October 15 through December 7.
During this period, eligible Medicare beneficiaries can make certain changes to their coverage, including switching Medicare Advantage plans, moving between Original Medicare and Medicare Advantage, or changing Medicare prescription drug coverage.
This should not be confused with the Medicare Advantage Open Enrollment Period or your initial opportunity to enroll in Medicare.
Medicare beneficiaries should review their coverage each year because plan premiums, benefits, drug formularies, pharmacy arrangements and provider networks can change. Medicare
Are There Special Enrollment Periods for Medicare?
Yes.
Certain life events can create a Special Enrollment Period, allowing you to make Medicare coverage changes outside the normal enrollment periods.
Examples can include moving outside your plan’s service area or losing certain other health coverage.
The rules and time limits depend on the event, so it is important to determine which Special Enrollment Period applies before making a change. Medicare
Special Enrollment Periods also exist in the individual health insurance market, although the qualifying events and rules are different. You can read our Pennsylvania Special Enrollment Period guide to understand how they work outside of Medicare.
When Can You Buy Medigap in Pennsylvania?
Medigap has its own important enrollment rules.
Your federal Medigap Open Enrollment Period generally lasts six months beginning when you’re 65 or older and enrolled in Medicare Part B.
During this period, insurers generally cannot deny you a Medigap policy because of pre-existing health conditions.
After this enrollment window, your ability to purchase a Medigap policy can be more limited and you may pay more unless you qualify for certain protections or guaranteed-issue rights.
This is why someone approaching Medicare eligibility should understand the difference between Medicare Open Enrollment and Medigap Open Enrollment. They are not the same thing. Medicare
How Much Does Medicare Cost in Pennsylvania?
There is no single price for Medicare coverage.
Your total costs can include combinations of:
- Part A premiums for people who don’t qualify for premium-free Part A
- Part A deductibles and cost sharing
- The Part B monthly premium
- The Part B deductible and coinsurance
- Medicare Advantage premiums and cost sharing
- Part D prescription drug premiums and drug costs
- Medigap premiums
Some Medicare costs are established federally, while Medicare Advantage, Part D and Medigap costs can vary by plan and location.
Pennsylvania also has assistance programs for some Medicare beneficiaries with limited income and resources.
Because Medicare amounts can change annually, check current-year costs before making coverage decisions rather than relying on figures from an older article.
How Should Pennsylvania Residents Compare Medicare Options?
A Medicare plan with a low monthly premium isn’t automatically the least expensive or best option.
Consider the entire coverage picture.
Start with your healthcare providers. If keeping a particular primary care physician, specialist or hospital is important, determine how the coverage works with those providers.
Then look at your prescriptions. Check whether your medications are covered and what you may pay for them.
You should also consider expected healthcare usage, deductibles, copayments, coinsurance and potential out-of-pocket exposure.
For Pennsylvania residents who travel frequently or spend part of the year in another state, the way a plan handles out-of-area care can also be important.
The Pennsylvania Department of Aging specifically recommends considering health needs, plan costs, doctors and hospitals, travel, medications, pharmacies, additional benefits and plan quality when comparing Medicare options. Pennsylvania
Where Can Pennsylvania Residents Get Medicare Help?
Pennsylvania residents have several resources available.
The federal Medicare program provides official coverage and enrollment information through Medicare.gov.
Pennsylvania also operates PA MEDI — Pennsylvania Medicare Education and Decision Insight, the state’s Medicare counseling program. PA MEDI provides free and unbiased Medicare counseling through Pennsylvania’s Area Agencies on Aging.
PA MEDI does not sell Medicare insurance products or recommend insurance agents or brokers. Pennsylvania
Licensed insurance agents can serve a different role by helping consumers understand and compare insurance products they are authorized to offer.
Getting Ready for Medicare in Pennsylvania
Medicare becomes much easier to understand when you break it into a series of decisions.
First, determine when you are eligible for Medicare Parts A and B and whether you need to actively enroll.
Next, decide whether you want to receive your coverage through Original Medicare or Medicare Advantage.
Then consider prescription drug coverage and, if you choose Original Medicare, whether Medicare Supplement coverage fits your needs.
Finally, compare your options based on your doctors, prescriptions, expected healthcare needs and budget.
There isn’t one Medicare arrangement that works best for every Pennsylvania resident. Understanding your options before an enrollment deadline gives you more time to make an informed decision.
Keystone Coverage Advisors helps Pennsylvania residents understand their health insurance and Medicare coverage options. If you’re approaching Medicare eligibility or reviewing your current coverage, contact us to discuss the options available in your area.