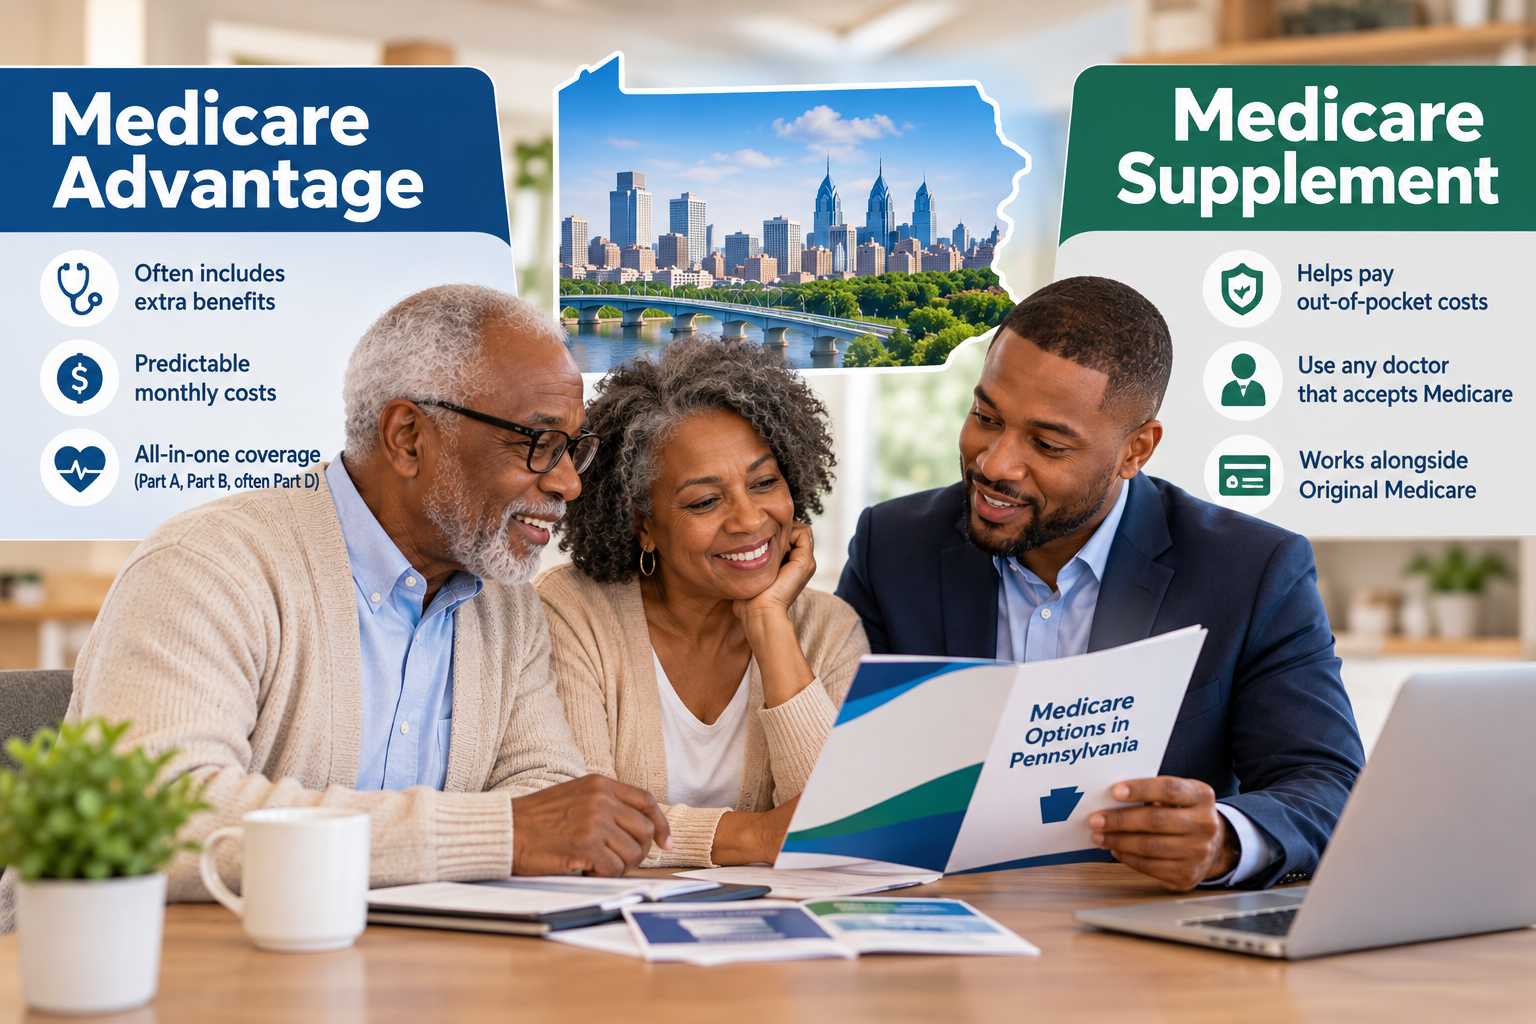
Comparing Medicare Advantage vs Medicare Supplement Pennsylvania options can be confusing, especially when you’re trying to determine which type of coverage fits your healthcare needs and budget. While both can play an important role in Medicare coverage, they work very differently..
Both options can help Pennsylvania Medicare beneficiaries manage healthcare costs, but they work very differently.
Medicare Advantage, also known as Medicare Part C, is an alternative way to receive your Medicare benefits through a private insurance company.
If you’re still learning how Medicare works, our Medicare in Pennsylvania: A Complete Guide explains Medicare Parts A, B, C and D and the basics Pennsylvania residents should understand.
Medicare Supplement Insurance, commonly called Medigap, works alongside Original Medicare to help pay some of the out-of-pocket costs that Original Medicare doesn’t cover.
Understanding that distinction is one of the most important steps when comparing your Medicare options.
Medicare Advantage vs Medicare Supplement Pennsylvania: Key Differences
Here’s the basic difference:
Medicare Advantage: You receive your Medicare benefits through a private Medicare-approved insurance plan.
Medicare Supplement: You remain enrolled in Original Medicare and purchase additional insurance to help cover certain costs left behind by Original Medicare.
You generally choose one approach or the other. You cannot use a Medigap policy to pay Medicare Advantage deductibles, copayments or premiums.
What Is Medicare Advantage?
Medicare Advantage plans are offered by private insurance companies approved by Medicare.
These plans provide your Medicare Part A and Part B benefits and must cover the medically necessary services covered by Original Medicare.
Most Medicare Advantage plans also include Medicare Part D prescription drug coverage, and plans may offer additional benefits that Original Medicare doesn’t cover, such as certain dental, vision or hearing services.
Depending on the plan, you may have:
- A network of doctors and hospitals
- Copayments for medical services
- Prior authorization requirements for certain services
- A defined annual out-of-pocket maximum
- Prescription drug coverage
- Additional benefits not provided by Original Medicare
Some Medicare Advantage plans have a $0 additional plan premium, but that does not mean Medicare itself is free. You generally must continue paying your Medicare Part B premium.
What Is Medicare Supplement Insurance?
Medicare Supplement Insurance — or Medigap — works differently.
Instead of replacing Original Medicare, a Medigap policy supplements it.
Original Medicare pays its share of Medicare-approved covered healthcare costs, and your Medigap policy can then help pay certain remaining costs according to the policy’s benefits.
Depending on the Medigap plan, coverage can help with expenses such as:
- Coinsurance
- Copayments
- Certain deductibles
- Other eligible Original Medicare cost-sharing
Some Medigap plans also provide limited foreign-travel emergency coverage.
You generally must have Medicare Part A and Part B to purchase a Medigap policy.
Prescription drug coverage is not included in modern Medigap policies, so someone who wants drug coverage generally needs to consider a separate Medicare Part D plan.
Doctor Networks Can Be a Major Difference
One of the biggest differences between Medicare Advantage and Medicare Supplement is how you access healthcare providers.
With Original Medicare plus Medigap, you can generally see any doctor or hospital in the United States that accepts Medicare.
Medicare Advantage plans may require you to receive non-emergency care from providers within the plan’s network and service area. Some plans allow out-of-network care, usually at a higher cost.
Certain Medicare Advantage plans may also require referrals to specialists.
For Pennsylvania residents who travel frequently or spend part of the year in another state, provider access can therefore be an important part of the decision.
How Do the Costs Compare?
There isn’t one option that’s automatically cheaper for everyone.
Medicare Advantage
With Medicare Advantage, you generally continue paying your Medicare Part B premium and may also pay an additional plan premium.
Depending on the plan, you may pay copayments, coinsurance or deductibles as you receive healthcare.
One important protection is that Medicare Advantage plans have an annual limit on what you pay out of pocket for covered Medicare services.
Medicare Supplement
With Medigap, you continue paying your Medicare Part B premium and pay a separate monthly premium for the Medigap policy.
The tradeoff is that the Medigap policy can reduce some of the healthcare costs you’d otherwise pay under Original Medicare.
Premiums vary based on the policy, location and other factors and may change over time.
This creates two different approaches to healthcare expenses:
Medicare Advantage may offer a lower monthly plan premium with more pay-as-you-use-it cost sharing.
Medigap may involve a higher monthly premium in exchange for reducing certain Original Medicare out-of-pocket expenses.
The right balance depends on your healthcare needs, budget and preferences.
What About Prescription Drugs?
This is another major difference.
Most Medicare Advantage plans include Medicare Part D prescription drug coverage.
Medigap policies sold today do not include prescription drug coverage.
Someone using Original Medicare with Medigap can enroll separately in a Medicare Part D prescription drug plan.
When comparing plans, don’t simply check whether your prescriptions are “covered.”
Look at:
- The plan’s formulary
- Drug tiers
- Copayments and coinsurance
- Preferred pharmacies
- Prior authorization requirements
- Your specific medications
Prescription needs can materially change which Medicare option makes sense.
Medicare Advantage Is Changing for 2027
Pennsylvania beneficiaries comparing coverage for 2027 should review their options carefully rather than assuming their current plan will remain unchanged.
CMS announced that the weighted average Medicare Advantage premium nationwide is projected to decline by more than 16% from 2026 to 2027. CMS has also finalized several policy and quality-measure changes affecting Medicare Advantage and Part D for 2027. Centers for Medicare & Medicaid Services
However, national averages don’t tell you what a particular Pennsylvania plan will cost or cover.
Individual plans can change their:
- Premiums
- Copayments
- Provider networks
- Prescription formularies
- Additional benefits
- Prior authorization requirements
That’s why Medicare beneficiaries should review their Annual Notice of Change and compare available plans each year.
Which Option Is Better for Pennsylvania Residents?
When comparing Medicare Advantage vs Medicare Supplement Pennsylvania options, there isn’t one choice that’s automatically best for everyone.
A Medicare Advantage plan may appeal to someone who prefers:
- Potentially lower monthly plan premiums
- An all-in-one approach
- Prescription coverage included in many plans
- Additional benefits offered by certain plans
- A defined annual limit on covered medical out-of-pocket expenses
Original Medicare with a Medigap policy may appeal to someone who values:
- Broad access to Medicare-participating doctors and hospitals
- Fewer network restrictions
- More predictable coverage of certain Original Medicare cost-sharing
- Flexibility when traveling within the United States
But those are starting points — not rules.
Your doctors, prescriptions, healthcare usage, budget and travel habits all matter.
When Should You Buy a Medicare Supplement Policy?
Timing is particularly important with Medigap.
Your federal Medigap Open Enrollment Period generally lasts six months beginning when you’re 65 or older and enrolled in Medicare Part B.
During this period, insurers generally cannot use medical underwriting to deny you a Medigap policy or charge you more because of health problems.
Outside protected enrollment situations, your ability to purchase or change Medigap coverage may be different.
That makes it important to understand your options before giving up existing coverage or switching between Medicare Advantage and Original Medicare with Medigap.
Start With the Way You Use Healthcare
Instead of asking:
“Which Medicare plan is the best?”
A better question is:
“Which type of Medicare coverage fits the way I actually use healthcare?”
Consider:
Doctors: Are your doctors and hospitals available under the coverage?
Prescriptions: How are your medications covered?
Travel: Do you regularly receive care outside Pennsylvania?
Budget: Would you rather pay more predictably each month or accept more cost sharing when you receive care?
Healthcare usage: How frequently do you see specialists or receive ongoing treatment?
Convenience: Do you prefer bundled coverage or separate Medicare, Medigap and Part D coverage?
Those questions can narrow the options considerably.
Get Help Comparing Medicare Options in Pennsylvania
Medicare Advantage and Medicare Supplement can both play important roles in Medicare coverage, but they’re designed very differently.
At Keystone Coverage Advisors, we help Pennsylvania residents understand their Medicare options and compare coverage based on their healthcare needs, prescriptions, providers and budget.
Before choosing coverage, take the time to understand not only the premium but also how the plan works when you actually need healthcare.
Have questions about Medicare coverage in Pennsylvania?
Contact Keystone Coverage Advisors to discuss your options.
Keystone Coverage Advisors is an independent insurance agency and is not connected with or endorsed by the U.S. government or the federal Medicare program. Plan availability, premiums, benefits, provider networks and prescription drug coverage vary by plan and location.